

Investment Strategy Brief | September 6, 2026
An Elephant in the Room: The U.S. National Debt
Executive Summary
-
Rising debt levels and higher interest costs have renewed attention on the long-term sustainability of U.S. fiscal policy.
-
The U.S. national debt is now larger than GDP, with interest costs garnering a record share of tax revenue.
-
High debt levels have proven problematic for other nations, but the U.S. reserve currency status likely provides more flexibility.
-
Disruptions to tariff policy due to the IEEPA ruling may temporarily lead to a wider deficit this year.
-
The U.S. still has time to establish a plan to gradually reduce deficits without material disruptions to markets or economic growth.
Rising bond yields have renewed concerns over the sustainability of government debt
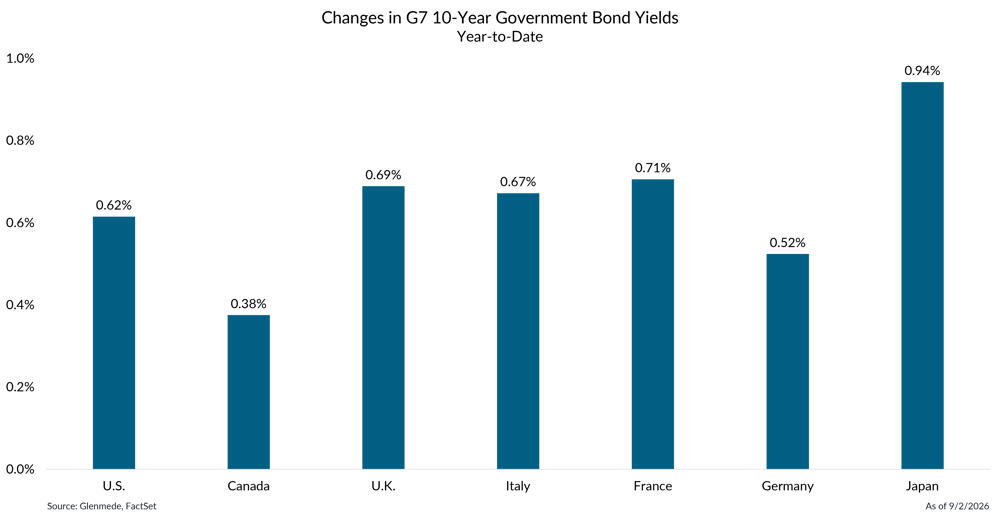
Shown is the year-to-date change in benchmark 10-year sovereign bond yields for G7 countries. Benchmark bonds represent the principal 10-year government security for each country.
-
Year-to-date, government bond yields have moved higher across all G7 countries, reflecting a broad increase in sovereign borrowing costs and renewed investor focus on government fiscal positions.
-
The recent rise in yields has renewed concerns about U.S. fiscal trajectory, as persistent deficits and growing debt balances continue to drive government borrowing higher.
The U.S. national debt is now as large as GDP, with interest costs garnering a record share of tax revenue
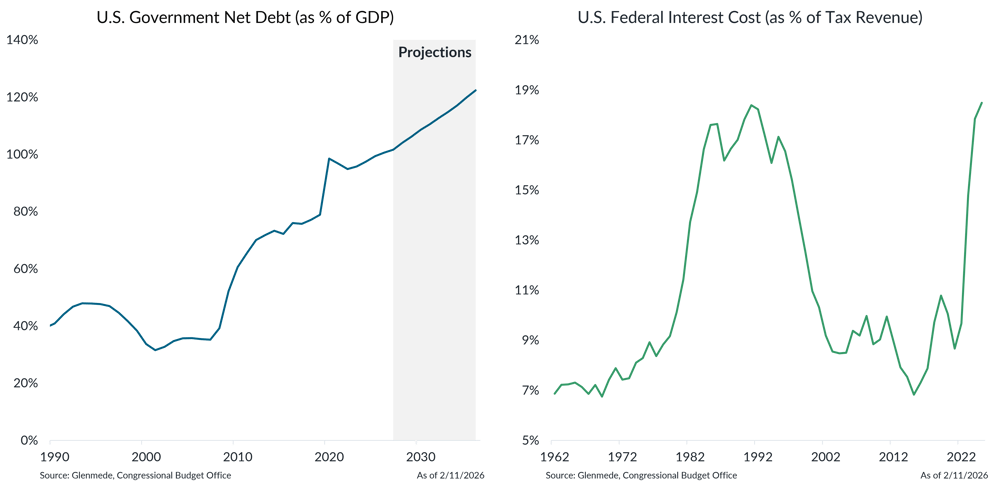
Shown on the left is U.S. government debt as a percent of gross domestic product (GDP), a measure of overall economic activity. U.S. government debt includes publicly held debt and excludes the portion of public debt that is held within the government by agencies or government trust funds, such as those for Social Security for periods after 1980. The figure for 2026 reflects the latest estimate from the Congressional Budget Office. The gray region represents projections from the Congressional Budget Office. Shown on the right are net interest costs (total interest paid minus interest received) as a percent of tax revenues collected each year. Actual results may differ materially from projections.
-
Net federal government debt, which excludes crossholdings between government agencies and trust funds, is now roughly equivalent in value to a year’s worth of economic activity in the U.S. and is projected to continue rising in the decade ahead.
-
As debt levels have increased and interest rates have moved higher, the cost of servicing the national debt has risen sharply and now consumes a growing share of federal tax revenues.
The U.S. likely has flexibility above 100% debt to GDP like other countries with reserve currencies
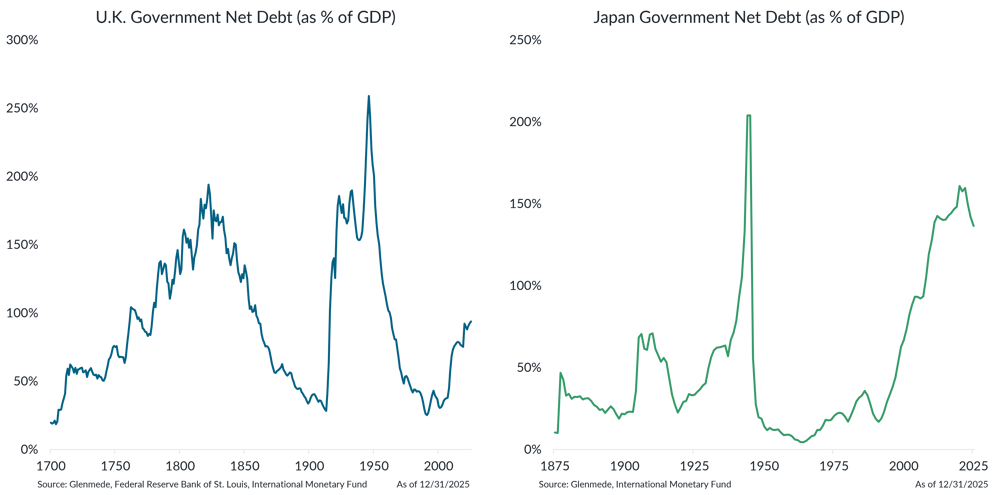
Shown on the left is government debt as a percent of GDP for the U.K. for periods after its formation in 1800 and for Great Britain prior to and including 1800. Shown on the right is Japan’s government debt as a percent of GDP, a measure of overall economic activity. Government debt includes publicly held debt and excludes the portion of public debt that is held within the government by other inter-governmental agencies or divisions for periods after 1980.
-
Historical experience suggests that countries whose currencies play a major role in the global financial system have often been able to sustain debt levels above 100% of GDP for extended periods of time.
-
The U.K. and Japan demonstrate that high debt burdens do not necessarily trigger an immediate crisis, though elevated debt levels can still create long-term economic and fiscal challenges.
The U.S. debt has been this high before and does not appear that different from other developed nations
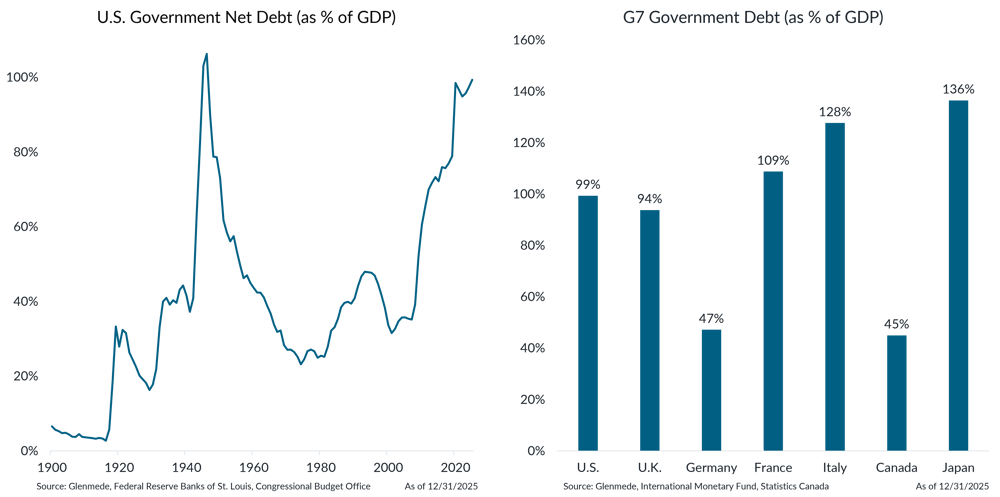
Shown on the left is U.S. government debt as a percent of U.S. gross domestic product (GDP), a measure of overall economic activity. U.S. government debt includes publicly held debt and excludes the portion of public debt that is held within the government by agencies or government trust funds such as those for Social Security for periods after 1980. Shown on the right is net government debt as a percent of GDP for the G7 countries. Canada’s net debt excludes social security program funds.
-
While current debt levels are high by recent standards, the U.S. has previously experienced debt burdens near current levels and ultimately reduced them over time through a combination of economic growth and fiscal adjustment.
-
The U.S. does not appear to be a significant outlier among developed nations, with several G7 peers carrying debt burdens that are comparable to or higher than current U.S. levels.
Tariff policy disruptions due to the IEEPA ruling are widening deficits, but likely for just this year
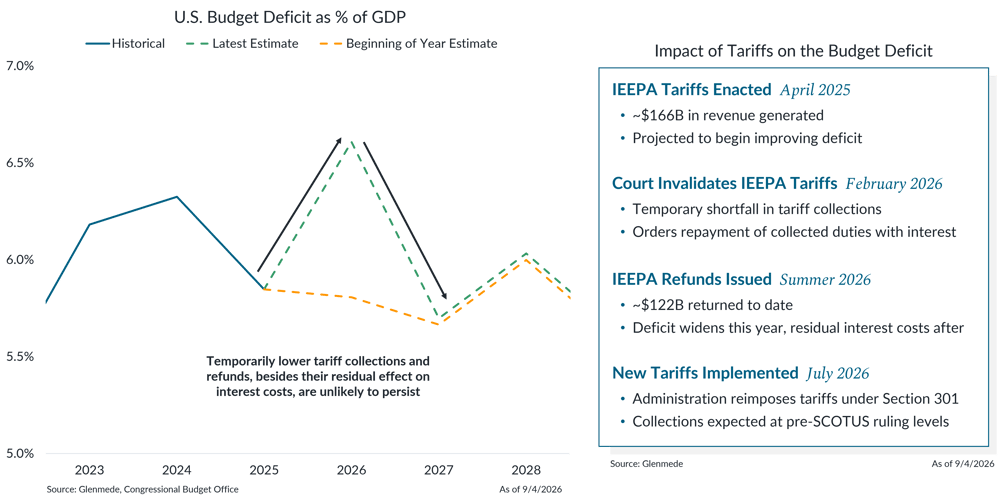
Shown is the U.S. budget deficit as a share of gross domestic product (GDP) in blue. Shown in orange are beginning-of-year estimates for the next 10 years. Shown in green are latest estimates, accounting for temporarily lower tariff collections in the wake of the Supreme Court’s (SCOTUS) ruling on tariffs enacted via the International Emergency Economic Powers Act (IEEPA), the refunding of previously collected tariffs, and any associated interest costs that result from larger deficits in 2026. Actual results may differ materially from projections or estimates.
-
Recent court-ordered tariff refunds may temporarily reduce the revenue generated by tariff policy, but current estimates still suggest tariffs should generate a meaningful amount of government revenue over the long run.
-
Although tariff revenue alone is unlikely to resolve the nation's fiscal challenges, it may help slow the pace of deficit growth relative to recent projections.
There still appears to be time to implement a gradual fiscal adjustment plan to change the trajectory
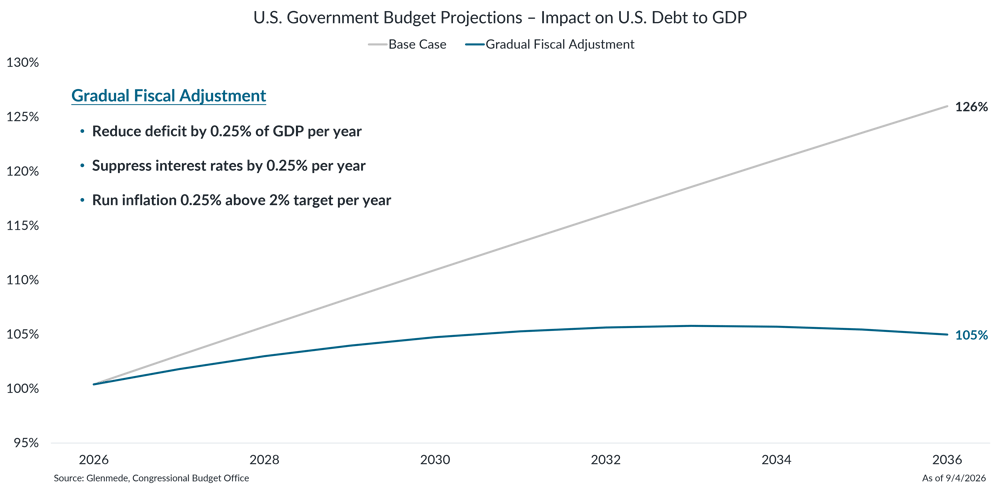
Shown are projections for U.S. government debt as a percent of U.S. gross domestic product (GDP), a measure of overall economic activity. U.S. government debt includes publicly held debt and excludes the portion of public debt that is held within the government by agencies or government trust funds such as those for Social Security. Base Case reflects a scenario in which current deficits continue for the next 10 years. Gradual Fiscal Adjustment reflects a scenario in which interest rates fall by 0.25%, allows inflation to run slightly higher than 2% at 2.25%, and the budget deficit is gradually reduced by 0.25% as a percentage of GDP per year. Actual results may differ materially from projections.
-
Relatively modest changes to fiscal policy can have a meaningful impact on the long-term debt outlook, assuming that policymakers have the political will to make them, particularly when implemented gradually over time.
-
A gradual adjustment process may give policymakers more flexibility to stabilize debt levels while minimizing disruptions to markets or economic growth.
For more in-depth information on this topic, please reach out to your Glenmede Relationship Manager.

This material is provided solely for informational and/or educational purposes and is not intended as personalized investment advice. When provided to a client, advice is based on the client’s unique circumstances and may differ substantially from any general recommendations, suggestions or other considerations included in this material. Any opinions, recommendations, expectations or projections herein are based on information available at the time of publication and may change thereafter. Information obtained from third-party sources is assumed to be reliable but may not be independently verified, and the accuracy thereof is not guaranteed. Any company, fund or security referenced herein is provided solely for illustrative purposes and should not be construed as a recommendation to buy, hold or sell it. Outcomes (including performance) may differ materially from any expectations and projections noted herein due to various risks and uncertainties. Any reference to risk management or risk control does not imply that risk can be eliminated. All investments have risk. Clients are encouraged to discuss any matter discussed herein with their Glenmede representative.